Navigating the world of digital assets can feel like a thrill ride, but when tax season arrives, early enthusiasm often turns into confusion. If you are stepping into the Web3 space, understanding how your transactions are treated by tax authorities is essential to staying compliant and avoiding costly penalties.
This crypto tax guide beginners 2026 breaks down everything you need to know about reporting requirements, taxable events, capital gains rules, and global tax treatments. Before diving into complex strategies, make sure you understand the foundational concepts covered in our guide on [What Is Cryptocurrency].
Why Is Cryptocurrency Taxed in 2026?
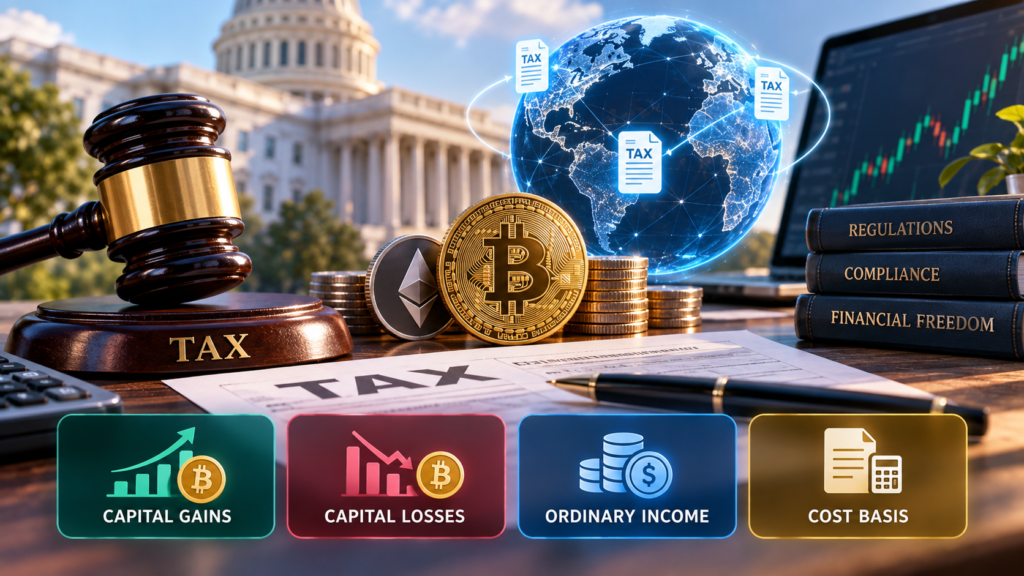
A common misconception among newcomers is that digital assets exist outside government jurisdiction. However, tax authorities worldwide treat cryptocurrencies not as traditional currency, but as property, intangible assets, or commodities. Because crypto holds monetary value and can generate income or capital appreciation, tax agencies strictly regulate and monitor transactions.
When you sell, trade, or earn digital assets, you create a potential tax obligation. Tax authorities treat these transactions similarly to trading stocks, real estate, or earning a traditional paycheck. Failure to report your crypto activity can result in audits, fines, or interest charges.
Key Tax Concepts for Digital Assets
To build a solid strategy—much like structuring your holdings using our guide on [How to Build Crypto Portfolio: link bài đã publish]—you must first grasp the core mechanisms governing crypto taxation:
-
Capital Gains: The profit made when selling or exchanging a digital asset for more than its purchase price (cost basis).
-
Capital Losses: The loss incurred when selling an asset for less than its purchase price. These can often offset gains.
-
Ordinary Income: Crypto earned as payment, staking rewards, mining yield, or airdrops, which is taxed at your standard income tax rate upon receipt.
-
Cost Basis: The original value of an asset (typically the purchase price in fiat currency plus associated fees), used to calculate net capital gains or losses.
Understanding this crypto tax guide beginners 2026 helps you keep clean records and make informed financial decisions throughout the year.
Common Taxable Events You Must Report
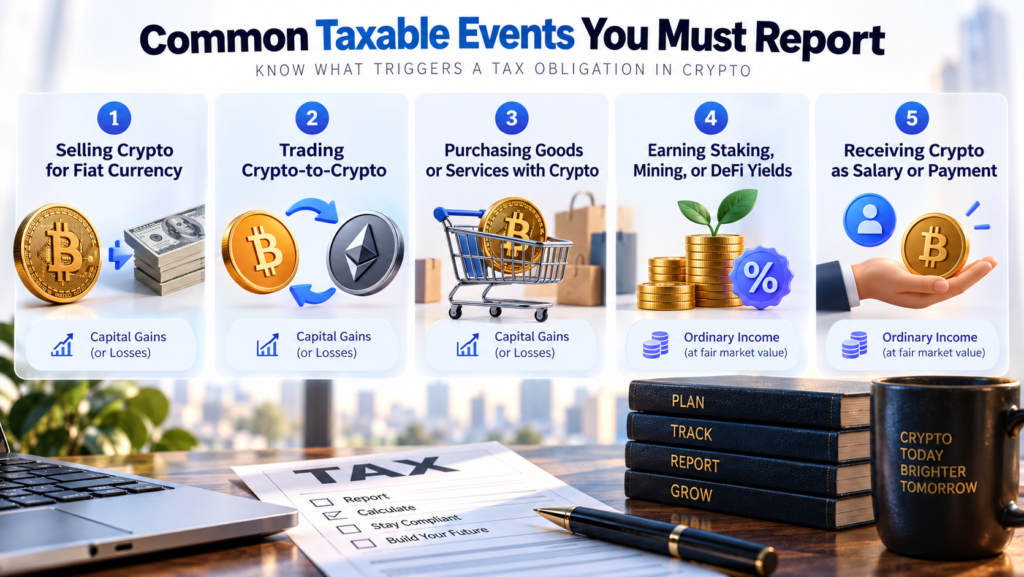
Every blockchain transaction leaves an indelible digital footprint, but not all on-chain activity is treated equally by tax authorities. Distinguishing routine administrative moves from taxable disposals is essential for keeping your reporting accurate and avoiding unexpected penalties.
Taxable Transactions Matrix
┌─────────────────────────────────────────────────────────────────────────┐
│ 1. Selling Crypto for Fiat Currency (e.g., USD, EUR, GBP)               │
├─────────────────────────────────────────────────────────────────────────┤
│ 2. Trading Crypto-to-Crypto (e.g., swapping BTC for ETH or stablecoins) │
├─────────────────────────────────────────────────────────────────────────┤
│ 3. Purchasing Goods, Merchandise, or Services with Crypto               │
├─────────────────────────────────────────────────────────────────────────┤
│ 4. Earning Yield via Staking, Network Mining, or DeFi Liquidity         │
├─────────────────────────────────────────────────────────────────────────┤
│ 5. Receiving Crypto as Earned Income, Salary, or Freelance Payment      │
└─────────────────────────────────────────────────────────────────────────┘
1. Selling Crypto for Fiat Currency
Off-ramping digital assets back into government-backed currency—whether converting Bitcoin, Ethereum, or altcoins into USD, EUR, or GBP—is the classic capital gains event. When you convert tokens to fiat, tax agencies evaluate the transaction by comparing the sale proceeds against your initial cost basis (the original purchase price plus exchange fees). If the asset appreciated while in your possession, you realize a taxable capital gain; if it lost value, you generate a capital loss that can potentially offset gains elsewhere in your portfolio.
2. Trading Crypto-to-Crypto
A common trap for Web3 newcomers is assuming that tax obligations only trigger when fiat currency is involved. Swapping one cryptocurrency directly for another—such as trading Bitcoin for Ethereum, exchanging an altcoin for a stablecoin like USDC, or routing trades through decentralized exchanges (DEXs)—is treated by tax authorities as a simultaneous two-part transaction:
-
A disposal of the original asset at its current fair market value in fiat.
-
An acquisition of the new asset, establishing its fresh cost basis.
Because the initial asset is considered “sold” at market rates during the swap, any profit accumulated since you originally bought it becomes immediately taxable, even if you never withdrew funds to a traditional bank account.
3. Paying for Goods and Services with Crypto
Using digital tokens to buy everyday consumer goods, pay independent contractors, or cover subscription services is legally classified as an asset disposal rather than a simple cash payment. When you scan a QR code to buy merchandise or cover a invoice with crypto, you are essentially selling that crypto at its real-time market value to fund the purchase. You must compute the fair market value in fiat at the exact time of the checkout and report any capital gain or loss realized relative to your original entry price.
4. Receiving Staking, Mining, or Yield Rewards
Participating in network consensus (Proof of Stake), running validation nodes, operating mining hardware, or providing liquidity to DeFi yield protocols creates a dual tax situation:
-
Income Tax upon Receipt: The moment you claim or gain control over newly minted staking rewards or yield payouts, their fair market value in fiat currency must be declared as ordinary income for that tax year.
-
Capital Gains on Future Disposal: That same fair market value at receipt becomes your starting cost basis. If you later sell, swap, or spend those rewarded tokens after they appreciate, you will owe capital gains tax on the additional profit.
5. Receiving Crypto as Salary or Freelance Payment
If you receive digital assets as compensation for work performed—whether as a full-time salary, freelance invoice payout, or gig payment—revenue authorities treat this value as standard earned income. The fiat market value of the tokens at the precise time they are deposited into your control dictates your taxable wages, subjecting them to ordinary income tax brackets (and local payroll/self-employment taxes where applicable).
To ensure your overall digital asset allocation aligns with your broader financial goals while navigating these tax requirements, review our detailed guide on How to Build Crypto Portfolio.
Non-Taxable Crypto Activities
Equally important as identifying taxable events is recognizing which routine blockchain interactions do not trigger a tax obligation. Misinterpreting these scenarios often leads to overpaying taxes, double-counting transactions, or creating unnecessary compliance headaches during reporting season.
-
Buying Cryptocurrency with Fiat Currency: Purchasing digital assets using traditional cash (such as USD, EUR, or GBP) and holding them in an exchange account or private wallet is completely tax-free. No tax is triggered at the moment of purchase, regardless of the purchase size. Instead, this transaction simply establishes your initial cost basis (the asset’s purchase price plus any acquisition fees) for future tax calculations.
-
Transferring Digital Assets Between Your Own Wallets: Moving funds across accounts or wallets that you personally own—such as transferring Bitcoin from a centralized exchange to a cold storage hardware wallet or shifting Ethereum between self-custodial addresses—does not count as a disposal. Because ownership remains unchanged, no gain or loss is realized. However, you should track any network gas or service fees incurred during the transfer, as these costs can sometimes be added to the asset’s cost basis or recorded as non-taxable wallet maintenance.
-
Holding (HODLing) Digital Assets: Simply retaining assets in your wallets generates zero tax liability, regardless of how dramatically their market price fluctuates or appreciates over time. Unrealized gains remain non-taxable until an actual disposal event occurs (such as a sale, crypto-to-crypto trade, or purchase using crypto).
-
Gifting Cryptocurrency (Within Statutory Limits): Gifting crypto directly to friends or family members is generally non-taxable for the giver up to designated annual exemption limits (such as the annual gift tax exclusion under US IRS rules). The recipient typically assumes your original cost basis and holding period, meaning they will only owe tax if and when they eventually dispose of the asset.
-
Donating Digital Assets to Registered Charities: Transferring tokens directly to approved 501(c)(3) non-profit organizations or registered charities creates a powerful win-win scenario. In many jurisdictions, donating appreciated crypto directly allows you to claim an itemized tax deduction equal to the asset’s full fair market value while avoiding capital gains taxes on the price appreciation.
Short-Term vs. Long-Term Capital Gains
Tax rates applied to realized crypto capital gains depend heavily on how long you hold the asset before selling or disposing of it. Applying strategic timing principles to your holdings can save you a substantial amount of money when filing tax returns.
| Holding Period | Asset Classification | Comprehensive Tax Treatment & Impact |
| Less than 1 Year (365 Days or Fewer) | Short-Term Capital Gain | Treated as short-term profit and taxed at standard ordinary income tax brackets (which can reach up to 37% in higher tax brackets). |
| 1 Year or Longer (366 Days or More) | Long-Term Capital Gain | Qualifies for preferential long-term capital gains tax rates, which are significantly lower (ranging from 0% to 20% depending on total income). |
Strategic Tax Planning & Optimization
-
Patience Pays Off: Holding an asset for just one day past the 12-month mark transitions your status from short-term to long-term, effectively cutting your potential tax rate on those profits by half or more in many tax brackets.
-
Tax-Loss Harvesting: If you hold underperforming assets trading below their original purchase price, you can strategically sell them at a loss before the end of the tax year. These realized capital losses can be used to directly offset realized capital gains across your portfolio, lowering your net taxable liability.
-
Record-Keeping & Batch Matching: Accurate transaction logging ensures you can apply appropriate accounting methods (such as FIFO, LIFO, or HIFO/Highest-In, First-Out where permitted) to optimize which specific tokens are deemed sold, further minimizing your total taxable gains.
Global Crypto Tax Rules (2026 Overview)
Crypto taxation rules vary across international jurisdictions. This crypto tax guide beginners 2026 provides a high-level comparison of regulatory frameworks in key regions:
United States (IRS)
The IRS crypto guidance classifies cryptocurrency as property. Key aspects include:
-
Capital gains taxes apply to disposals, ranging from 0% to 20% for long-term gains depending on income brackets (plus net investment income taxes if applicable).
-
Short-term gains are taxed at ordinary income tax brackets (up to 37%).
-
Income from staking, mining, and wages is taxed as ordinary income upon receipt.
United Kingdom (HMRC)
According to HMRC crypto guidance, digital assets are subject to Capital Gains Tax (CGT) upon disposal:
-
Individual CGT allowances apply before tax kicks in.
-
Trading activities or receipt of tokens as earnings incur Income Tax and National Insurance contributions.
-
Special pooling rules (Same Day, 30-Day, and Section 104 rules) govern how cost basis is determined for matching trades.
Australia (ATO)
The Australian Taxation Office (ATO) treats cryptocurrency as property for Capital Gains Tax purposes:
-
Holding an asset for more than 12 months makes individual taxpayers eligible for a 50% CGT discount.
-
Chain splits, staking, and airdrops trigger ordinary income obligations upon receipt.
India (ITD)
India maintains a strict, highly specific framework for Virtual Digital Assets (VDAs):
-
A flat 30% tax applies to all gains from crypto transfers, with no deduction allowed except for the cost of acquisition.
-
Losses from one crypto transaction cannot offset gains from another.
-
A 1% Tax Deducted at Source (TDS) applies to all disposal transactions exceeding set thresholds.
Crypto Tax Software and Tools
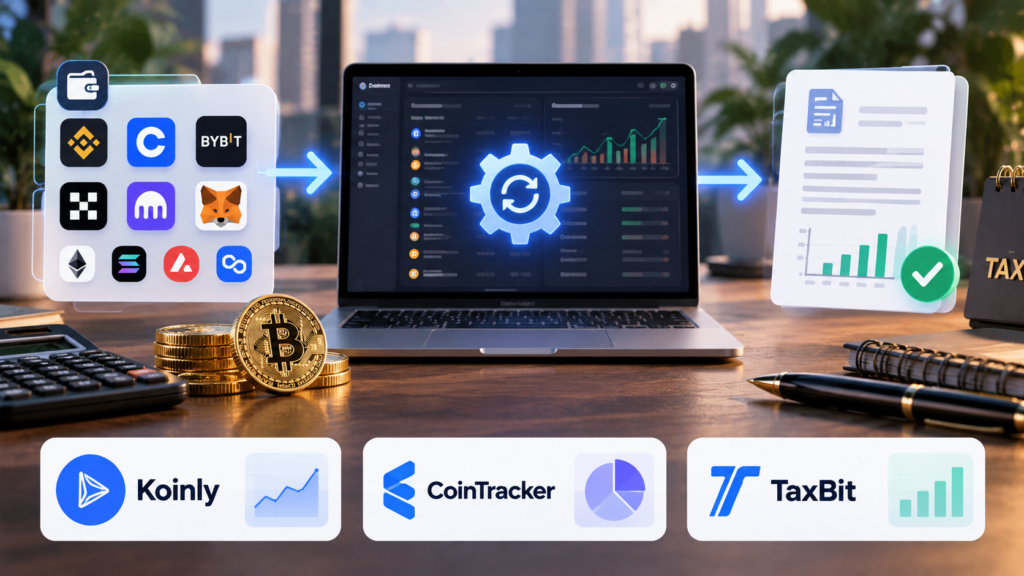
Manually tracking trades, gas fees, staking payouts, and transfers across multiple exchanges and wallets is time-consuming and error-prone. Modern tax software simplifies this process dramatically.
How Crypto Tax Tracking Works
┌──────────────────┐    ┌──────────────────┐    ┌──────────────────┐
│ Connect Exchange │ ─► │ Automatic Matching│ ─► │ Generate Form /  │
│ APIs & Wallets   │    │ & Cost Calculation│    │ Tax Report       │
└──────────────────┘    └──────────────────┘    └──────────────────┘
Top tracking services recommended for beginners in 2026 include:
-
Koinly.io: Integrates directly with hundreds of exchanges and blockchains, generating country-specific tax reports automatically.
-
CoinTracker: Offers seamless wallet sync, real-time portfolio management, and automated capital gains calculations.
-
TaxBit: Designed for enterprise and retail users, providing real-time tax tracking and direct integration with major trading platforms.
Frequently Asked Questions (FAQ)
1. Does transferring cryptocurrency between my own wallets or exchange accounts trigger a taxable event?
No, simply moving digital assets between wallets, storage devices, or exchange accounts that you personal control is not considered a taxable event. Tax authorities view this action as a non-taxable wallet-to-wallet transfer rather than a disposal, meaning no capital gains or losses are realized during the move.
However, you must account for the transaction fees (gas fees) paid to execute the transfer. Depending on your local tax regulations, these blockchain network fees can often be added to the cost basis of the transferred asset or treated as an allowable investment expense. Furthermore, it is critical to keep meticulous logs of these self-transfers; without accurate transaction records linking your addresses, tax software or auditors might misinterpret an internal transfer as a taxable sale or income event.
2. How do capital losses work in crypto, and can I use them to write off my taxes?
Yes, you can leverage capital losses to reduce your overall tax liability through a process commonly referred to as tax-loss harvesting. A capital loss occurs when you sell, trade, or dispose of a digital asset for less than its original purchase price (cost basis). In most jurisdictions, these realized losses can directly offset any capital gains you achieved within the same tax year across crypto, stocks, or other investments.
If your total capital losses exceed your capital gains for the year, many tax authorities allow you to deduct a specific portion of the remaining net loss against your ordinary income (for example, up to $3,000 annually under US IRS guidelines). Any unused net losses beyond that statutory limit can typically be carried forward into future tax years indefinitely to offset future gains. Keep in mind that specific rules—such as wash-sale rules—may apply depending on your region, so maintaining exact purchase and disposal records is vital.
3. How do tax authorities track cryptocurrency transactions and enforce compliance?
Tax agencies globally utilize advanced, multi-layered tracking frameworks to monitor digital asset transactions, making crypto far from anonymous. First, major centralized cryptocurrency exchanges (CEXs) are legally required to adhere to strict Know Your Customer (KYC) and Anti-Money Laundering (AML) regulations. In many regions, exchanges automatically report user trading activity and year-end account balances directly to government agencies using standardized reporting frameworks (such as Form 1099-DA in the United States or the OECD’s Crypto-Asset Reporting Framework/CARF internationally).
Second, because public blockchains operate as immutable, permanent ledgers, every transaction, wallet address, and smart contract interaction is permanently recorded. Revenue service agencies deploy sophisticated blockchain analytics and forensic software to map out pseudonymous wallet clusters, linking on-chain activity back to verified exchange accounts. As a result, unrecorded disposals, hidden staking rewards, or undisclosed wallet addresses can easily trigger automated compliance flags, inquiry letters, or formal audits.
Conclusion
As the digital asset ecosystem continues to mature, tax enforcement mechanisms are becoming increasingly sophisticated globally. While the decentralized nature of Web3 technology offers unprecedented financial autonomy, it does not exempt investors from national fiscal duties. Proactively managing your tax footprint is as crucial to long-term success as selecting winning assets or building a balanced investment portfolio.
By implementing the foundational principles outlined in this crypto tax guide beginners 2026, you equip yourself to maintain accurate transaction histories, distinguish between taxable disposals and non-taxable wallet movements, and leverage tax-saving strategies like long-term holding discounts or loss harvesting. Integrating automated portfolio-tracking tools early in your journey eliminates the stress of last-minute calculations, ensuring your focus remains on capital growth and security.
Ultimately, staying compliant protects your wealth from unnecessary fines, legal disputes, and administrative stress. Make tax tracking a routine part of your ongoing portfolio management rather than an afterthought at the end of the year.
Disclaimer: This document is strictly for educational purposes and does not constitute official tax, legal, or financial advice. Crypto regulations change rapidly, and rules vary greatly depending on where you reside. Always consult a certified tax professional or specialized accountant to review your personal situation.